Key Takeaways:
-
- BNPL products now need instant credit checks, flexible installment structures, merchant settlement tools, and fraud monitoring working together, not as separate add-ons.
- Picking the right BNPL app development companies comes down to whether you need a consumer wallet, a merchant-side plugin, or a bank-grade lending engine.
- Regulatory readiness and risk-scoring logic shape your budget and timeline more than screen design ever will.
- A working BNPL build generally lands between $45,000 and $130,000+, shaped by integrations, geography, and underwriting complexity.
- Launching a lean version first and layering in advanced scoring or merchant tools later keeps early costs manageable for founders.
Buy now, pay later has changed enormously since it just meant a store card and a mail-in form. Today it means three taps at checkout and an approval before the order even ships. That speed is the product now, and customers notice the moment it slows down.
This shift has changed who builds the payment layer. Banks, retailers, and independent founders are all racing to own that checkout moment. Most are turning to top BNPL app development companies because building lending infrastructure from scratch takes a lot of effort.
Building a kind of product touches far more than a payment button. Your roadmap will likely include merchant onboarding and payout cycles, real-time credit decisioning, installment scheduling, and identity verification. It also involves regional compliance across currencies, dispute resolution workflows, customer credit-limit management, and reporting dashboards for both lenders and merchants.
Top 10 BNPL App Development Companies Worth Shortlisting in 2026-2027
Each company below brings a different mix of strengths. Some are built for lean consumer apps, others for bank-scale credit infrastructure. This snapshot ranks the best BNPL companies by fit before the full breakdown further down.
Company |
Strongest Fit |
Business Stage |
BNPL/Fintech Product Potential |
Technology Strength |
| Dev Technosys | Custom BNPL & embedded lending | Startup to Enterprise | High | Mobile, AI, Cloud, Payments |
| IBM | AI-driven credit decisioning | Enterprise | High | AI, Cloud, Analytics |
| Globant | Consumer-first BNPL experiences | Startup to Enterprise | Strong | UX, AI, Product Engineering |
| TCS | Large-scale banking rollouts | Enterprise | Strong | Cloud, Data, Enterprise Tech |
| Coforge | Back-office lending modernization | Mid-size to Enterprise | Strong | Application Development, Data |
| EPAM Systems | Complex fintech architecture | Enterprise | Strong | Product Engineering |
| Tech Mahindra | Connected merchant ecosystems | Mid-size to Enterprise | Strong | AI, Cloud, Automation |
| Xebia | Cloud-native scaling | Growing Businesses | Strong | Cloud, DevOps, Data |
| Capgemini | Enterprise transformation programs | Enterprise | Strong | Cloud, Data & AI |
| UST | Connected finance modernization | Mid-size to Enterprise | Strong | Digital Engineering |
Answer a few quick questions and our experts will share a tailored project estimate.
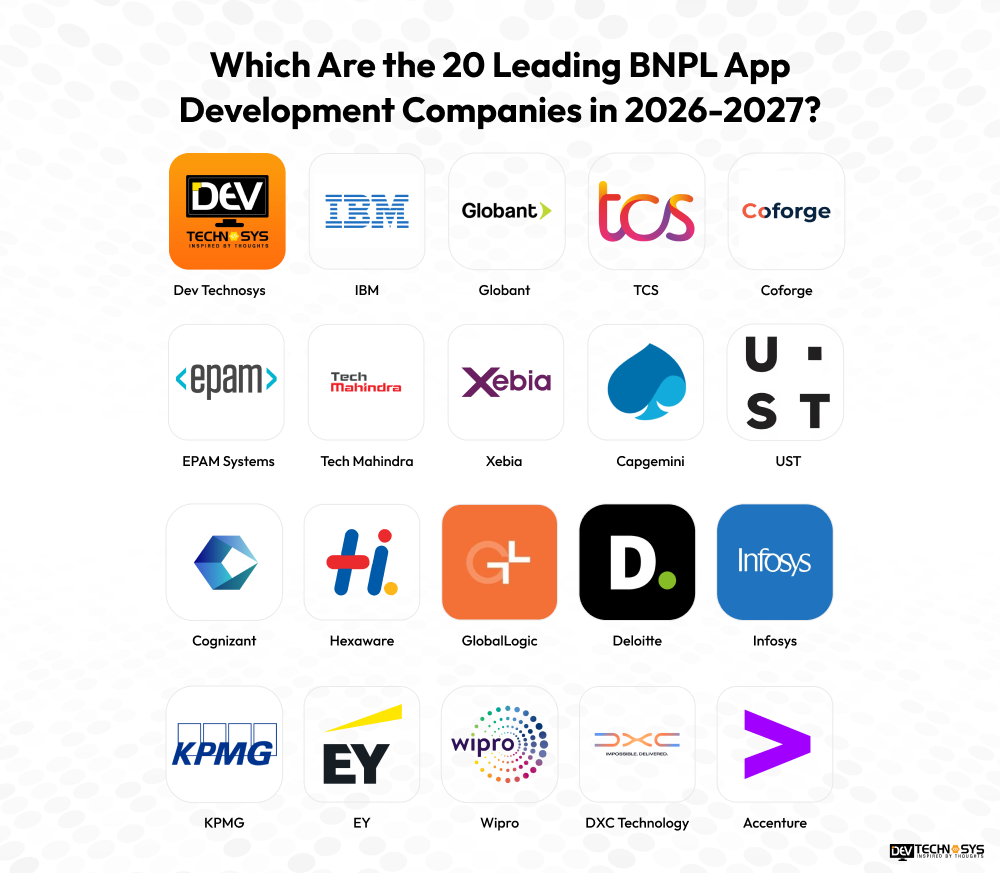
Which Are the 20 Leading BNPL App Development Companies in 2026-2027?
Shortlisting gets easier once you know your own lending model. A retailer adding installment checkout needs a very different build than a standalone credit marketplace. Below are 20 companies worth researching, ranked by engineering depth and typical BNPL fit.
1. Dev Technosys
Dev Technosys stands out among leading BNPL companies for founders who need a lending product built around their actual repayment logic, not a rebranded template. The company has delivered 2,900+ projects across 71+ countries over 15+ years, working across mobile, cloud, and AI-driven finance tools.
Its strength lies in stitching together credit scoring, merchant settlement, and compliance layers into one coherent product. This flexibility is why many founders treat it as a benchmark among BNPL app development companies before comparing anyone else.
Top BNPL App Development Services:
- Custom BNPL App Development
- Fintech & Ewallet App Development
- Merchant Checkout Integration
- Credit Scoring & Risk Engines
- AI-Powered Fraud Detection
- BNPL App Maintenance & Enhancement
2. IBM
IBM earns its place when a BNPL product leans heavily on data science rather than simple rule-based approvals. A lender processing millions of transactions can use its analytics stack to spot repayment risk patterns before they turn into defaults, something smaller vendors rarely have the infrastructure to handle well.
Top Services:
- AI & Machine Learning
- Cloud Computing
- Data Analytics
- Enterprise Software
- Cybersecurity
- Digital Transformation
3. Globant
Globant fits founders chasing adoption through experience rather than feature count alone. A BNPL app wins repeat use through fast approvals and a checkout flow that doesn’t feel like a loan application. Businesses exploring banking & finance software development with a strong consumer lens often shortlist Globant early in vendor research.
Top Services:
- Digital Product Development
- UX/UI Engineering
- AI Solutions
- Mobile Development
- Cloud Services
- Digital Experience Design
4. TCS
TCS suits lenders with sprawling technology footprints already in place. A BNPL rollout across several countries, currencies, or merchant categories needs a partner comfortable working inside existing core-banking systems. This makes TCS a common pick among top BNPL development companies for institutions expanding an existing credit business rather than launching from zero.
Top Services:
- Enterprise Application Development
- Cloud Solutions
- Data & Analytics
- AI Development
- Digital Transformation
- Accounting Software
5. Coforge
Coforge tends to shine on the operational side of lending, not just the customer app. Underwriting workflows, merchant reconciliation, and backend reporting often need as much engineering attention as the mobile screens users actually see. For businesses modernizing legacy loan systems while adding a modern front end, Coforge offers a practical middle ground between rebuild and full replacement.
Top Services:
- Application Development
- Digital Transformation
- Cloud Services
- Data Analytics
- Process Automation
- Application Modernization
6. EPAM Systems
EPAM is worth a look when architecture decisions matter more than launch speed. A platform running multiple products, real-time settlement, and layered risk scoring needs engineers who think in systems, not screens. Some enterprise buyers researching Buy Now Pay Later app development companies for multi-product lending suites lean toward EPAM specifically for this depth.
Top Services:
- Product Engineering
- Mobile Development
- Cloud Engineering
- AI & Data Solutions
- API Development
- Digital Experience Engineering
7. Tech Mahindra
Tech Mahindra fits businesses building a connected lending ecosystem that stretches beyond the app itself. Merchant partners, credit bureaus, and payment networks all need to talk to each other reliably. That connective layer is where this team tends to add value. Its broader portfolio also touches NFT marketplace development, useful for fintech groups running adjacent digital-asset products alongside lending.
Top Services:
- AI & Automation
- Cloud Engineering
- Data Engineering
- Connected Solutions
- Digital Transformation
- Merchant Integration Consulting
8. Xebia
Xebia matters most once transaction volume becomes unpredictable. A BNPL startup that suddenly gets featured by a major retailer needs infrastructure that absorbs the spike without downtime. Cloud-native architecture and DevOps discipline are what make that kind of scaling possible without a rebuild six months later. Founders comparing top BNPL software development companies for rapid growth phases often weigh Xebia against smaller boutique shops.
Top Services:
- Cloud-Native Development
- DevOps
- Data Engineering
- Application Modernization
- Agile Product Development
- Cryptocurrency Exchange Apps
9. Capgemini
Capgemini leans toward larger transformation mandates rather than single-product builds. A bank rolling out BNPL as part of a wider digital strategy, alongside existing card products and savings tools, benefits from a partner already fluent in enterprise-scale change management. That makes Capgemini a strong fit for financial institutions that need BNPL to operate as part of a broader, connected banking ecosystem rather than as a standalone product.
Top Services:
- Digital Engineering
- Cloud Transformation
- Data & AI
- Application Modernization
- Cybersecurity
- Enterprise Technology
10. UST
UST works well for lenders migrating off dated infrastructure while introducing BNPL as a new revenue line. Digital engineering paired with data modernization helps older financial institutions add credit products without rebuilding their entire technology base. This combination puts UST on the radar for BNPL solution development companies’ searches from mid-size regional banks specifically.
Top Services:
- Digital Engineering
- Cloud Solutions
- Data & Analytics
- Application Development
- Technology Modernization
- Blockchain Development Services
11. Cognizant
Cognizant fits best when BNPL sits inside a much larger digital banking program. Institutions juggling mobile apps, analytics platforms, and enterprise systems at once often bring Cognizant in for the connective engineering work between all three. That makes Cognizant a practical choice for BNPL providers that need to connect lending, payments, customer data, and digital channels.
Top Services:
- Digital Product Engineering
- Cloud Solutions
- AI & Analytics
- Mobile Application Development
- Customer Experience Solutions
- Enterprise Technology
12. Hexaware
Hexaware suits businesses with working digital infrastructure that simply feels outdated to users. Moving toward cloud-based lending workflows and automated approvals can modernize the customer experience without a ground-up rebuild. Its regional strength also covers e-wallet apps in Middle East deployments, relevant for lenders targeting GCC markets.
Top Services:
- Cloud Engineering
- Application Modernization
- Data Engineering
- AI & Automation
- Technology Modernization
- Regional Compliance Consulting
13. GlobalLogic
GlobalLogic leans into product engineering over consulting, which suits founders who want a genuinely differentiated app rather than an installment calculator with a new coat of paint. Mobile experience and API design tend to be where this team invests the most effort. That makes GlobalLogic a better fit for BNPL products where user experience, API connectivity, and product differentiation matter.
Top Services:
- Product Engineering
- Mobile App Development
- UX/UI Development
- Cloud Engineering
- API Development
- Digital Experience Solutions
14. Deloitte
Deloitte becomes relevant once BNPL is a business transformation question, not just a technical one. Institutions realigning strategy, data governance, and operating models before writing a line of code often bring Deloitte in at that earlier planning stage. Some of its fintech advisory work also intersects with smart contract development for lenders exploring blockchain-based settlement rails.
Top Services:
- Digital Strategy
- Data & Analytics
- Cybersecurity
- Digital Transformation
- Technology Advisory
- Regulatory Strategy Consulting
15. Infosys
Infosys fits banks modernizing legacy loan platforms while bolting on new digital capabilities. Analytics, automation, and cloud migration typically come bundled together in these engagements, rather than being treated as separate projects. This makes it suitable for lenders looking to introduce BNPL without rebuilding their entire technology environment from scratch.
Top Services:
- Digital Engineering
- Application Development
- Cloud Services
- Data Analytics
- Automation
- Technology Consulting
16. KPMG
KPMG works best where governance, risk, and technology decisions need to sit at the same table. Enterprise lenders navigating multiple regulatory jurisdictions often value this advisory layer as much as the actual build work. Its strength is particularly relevant when BNPL expansion depends on getting risk frameworks and regulatory processes right across markets.
Top Services:
- Digital Transformation
- Data & Analytics
- Cybersecurity
- Technology Strategy
- Risk Advisory
- Lottery App Development
17. EY
EY fits organizations where technology strategy needs to align tightly with business objectives before development starts. Established lenders bringing in outside strategy support alongside their build partner often add EY at the planning stage. For BNPL initiatives, this approach can help define the operating model, risk priorities, and technology roadmap before development begins.
Top Services:
- Technology Strategy
- Digital Transformation
- Data Solutions
- Technology Consulting
- Application Modernization
- Digital Advisory
18. Wipro
Wipro suits lenders that want digital product work paired with broader enterprise modernization. A BNPL platform connecting to core banking, CRM, and analytics systems benefits from a partner already embedded in that wider technology stack. It remains a recognizable name among top BNPL companies for enterprise clients. That broader integration capability can help financial institutions fit BNPL into existing customer and lending ecosystems.
Top Services:
- Digital Engineering
- Cloud Services
- Application Modernization
- Data Analytics
- AI & Automation
- Banking Apps
19. DXC Technology
DXC suits large institutions running complex, older IT environments. A BNPL platform layered onto legacy enterprise systems and managed infrastructure usually calls for a partner experienced in exactly that kind of modernization work, which is why it appears on shortlists for best BNPL technology companies serving legacy-heavy banks. Its value is strongest when the BNPL rollout has to coexist with established banking infrastructure rather than replace it outright.
Top Services:
- Application Modernization
- Cloud Transformation
- Enterprise Technology
- Managed IT Services
- Data Solutions
- Application Services
20. Accenture
Accenture rounds out this list for institutions running large, multi-market lending programs. Its combination of consulting, cloud engineering, and data science suits banks treating BNPL. Alongside, adjacent work includes blockchain services for fintech groups diversifying their product lines. It is therefore better suited to BNPL programs that require coordinated transformation across markets, channels, data platforms, and lending operations.
Top Services:
- Digital Strategy Consulting
- Cloud Engineering
- Data & AI
- Enterprise Modernization
- Cybersecurity
- Regional Banking Integrations
How to Choose the Right BNPL App Development Company in 2026-2027?
A low quote tells you very little about long-term fit. What matters more is how a partner approaches credit risk, compliance, and future scaling. Here’s what actually separates the best BNPL software development companies from vendors who only build the interface.
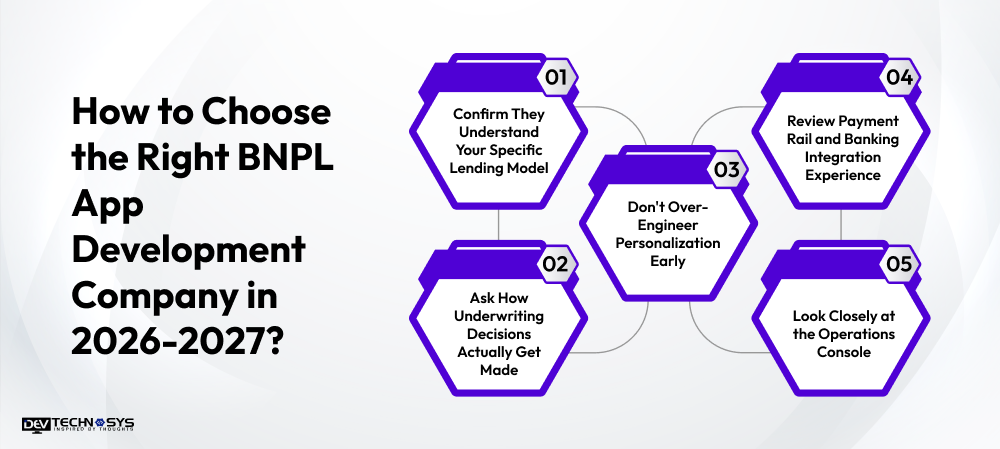
1. Confirm They Understand Your Specific Lending Model
A merchant checkout plugin, a standalone lending app, and a bank-embedded credit line all need different underlying architecture. Share your revenue model and target customer before letting the conversation jump to feature lists.
2. Ask How Underwriting Decisions Actually Get Made
If credit approval drives your business, dig into data sources, scoring logic, and how rejected applicants get an explanation. A team that only talks about the checkout screen probably hasn’t built the risk engine behind it.
3. Don’t Over-Engineer Personalization Early
Early-stage BNPL apps rarely need complex behavioral modeling. Simple rules based on order size, repayment history, and basic identity checks often work fine at launch. Save the advanced scoring models for once you have real repayment data to train on.
4. Review Payment Rail and Banking Integration Experience
Settlement speed depends heavily on which payment rails and banking APIs a team has actually shipped before. Ask about reconciliation processes too, since mismatched settlement records cause more support tickets than almost anything else in lending apps.
5. Look Closely at the Operations Console
A slick customer-facing app matters less if your risk team needs a developer every time a lending policy changes. Push for an admin layer that lets operations staff adjust limits, repayment terms, and merchant settings independently.
Security, Privacy & Compliance Considerations for BNPL Apps
BNPL platforms sit on sensitive ground: identity documents, credit history, payment credentials, and detailed transaction logs. Founders should look past application-level security and check a partner’s certifications, data governance practices, and compliance track record.
Area |
What Founders Should Check |
| Account Protection | Secure authentication, MFA, session management, and access controls |
| Identity & Credit Data | Encryption, data minimization, secure storage, and controlled access |
| Payment Data | Secure payment gateways and protected transaction workflows |
| Merchant Access | Role-based permissions for merchants, admins, and support teams |
| Underwriting Logic | Auditable, explainable, and reviewable credit decisions |
| API Security | Authentication, validation, rate limiting, and monitoring |
| Privacy Management | Consent, retention, deletion, and user-data controls |
| Cloud Security | Secure infrastructure, backups, monitoring, and restricted access |
| Security Testing | Vulnerability assessment, penetration testing, and remediation |
| Compliance Readiness | Processes aligned with lending and consumer credit regulations |
Security Certifications & Privacy Standards to Look For
Founders comparing top BNPL companies should ask which frameworks and certifications actually back a vendor’s day-to-day security practices, not just its marketing page.
Standard / Certification |
Why It Matters for a BNPL App |
| ISO 27001 | Shows a structured information security management system with real risk controls |
| ISO Standards | Signals formalized quality, security, or management processes across a vendor’s operations |
| SOC 1 | Offers assurance over controls tied to financial reporting processes |
| SOC 2 | Covers security, availability, confidentiality, and privacy controls |
| GDPR | Matters when personal data from EEA users passes through the app |
| CCPA | Applies to businesses handling personal data from California consumers |
Certifications shouldn’t be treated as a checklist item alone. Ask which certifications a vendor currently holds, what scope each one covers, and how those controls actually apply to your specific lending build.
What Should Your Development Partner Handle?
At minimum, confirm how the team plans to protect:
- User accounts and authentication
- Credit and underwriting data
- Repayment and settlement workflows
- Merchant and admin-level permissions
- Third-party payment and credit-bureau APIs
- Cloud infrastructure and backups
- Data retention and deletion policies
- Regional lending compliance requirements
Your exact obligations shift based on the data you collect, your lending model, and the markets you serve. A BNPL platform running across borders may need to satisfy GDPR, CCPA, and regional consumer-credit rules simultaneously. Whereas bank partnerships often demand additional formal audits too.
Final Words
Choosing a BNPL app development firm is ultimately a business and risk decision, not just a technology decision. The right partner should understand your lending model, payment workflows, customer journey, fraud controls, integrations, security requirements, and applicable compliance obligations.
The 20 companies covered in this guide bring different strengths. So, your final choice should depend on your product scope, target market, budget, scalability needs, and regulatory environment. Before signing a development contract, evaluate technical expertise, security practices, fintech experience, communication, post-launch support, and ownership terms.
A capable BNPL development partner can help you build a platform that is secure, compliant, scalable, and commercially ready.
FAQs
1. How much does it cost to build a BNPL app in 2026-2027?
Costs typically fall between $30,000 and $150,000, shaped by feature scope, platform count, credit-scoring complexity, and compliance requirements across regions. A lean MVP costs meaningfully less than a full enterprise lending platform with multi-market support.
2. How do I stop my BNPL app from feeling like every other installment tool on the market?
Solve one specific friction point well, whether that’s approval speed, repayment flexibility, or merchant-side settlement transparency. Copying existing checkout flows rarely builds loyalty; solving a genuine pain point for either shoppers or merchants does.
3. What happens if my BNPL app suddenly gets a surge of new users?
Backend infrastructure needs to handle growth before it happens, not after. That means scalable databases, caching layers, fraud monitoring built for volume, and load testing done well ahead of any marketing push or retail partnership announcement.
4. Should I retain full ownership of my BNPL app’s source code?
Yes, insist on clear ownership of source code, design assets, documentation, and underlying data. Get intellectual property terms, repository access, licensing details, and transfer conditions written into the contract before any development work actually begins.
5.What should I ask Top Buy Now Pay Later Companies before signing a contract?
Ask about prior lending or credit-product experience, not just general app development history. Cover security certifications, ongoing maintenance costs, ownership rights, team structure, and support after launch, and get scope clearly defined to avoid cost creep later.